

Schwab Mobile analysis by Appwee
I approach finance apps differently from ordinary mobile tools: convenience matters, but clarity and control matter more. Schwab Mobile is built for people who want investing, research, trading, and banking access in one place rather than switching between several services. After spending time with it, I found its strongest quality is the way it brings a broad Charles Schwab account experience onto a phone, while its main weakness is that the amount of information can feel demanding when you only want to check something quickly.
The app is developed by The Charles Schwab Corporation and sits in the finance category. It is free to download, with an Everyone content rating, so the basic cost barrier is low. That does not mean every financial activity inside it is free or suitable for every user; the app is a gateway to Schwab services, and the value depends heavily on what kind of account holder or investor you are. I would not judge it like a budgeting app or a simple stock-price widget.
What Schwab Mobile feels like in everyday use
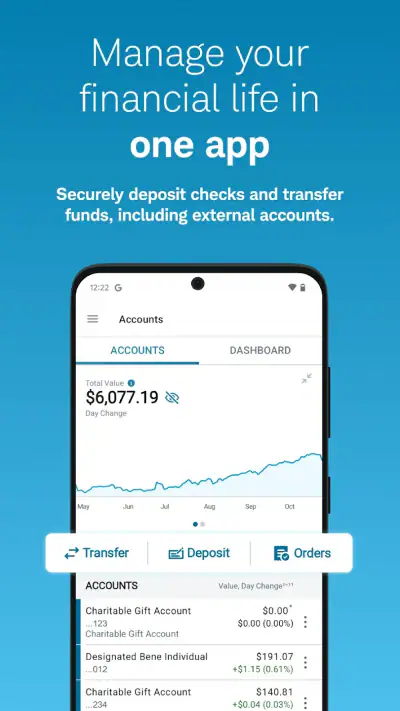
The first thing I noticed is that this is not designed around one narrow task. The store summary describes an experience covering investing, research, banking, trading, and more, and that broad purpose comes through in the way the app is organized. Instead of treating your brokerage account as a separate destination from your cash activity, it gives you a central mobile place to review the financial picture connected to Schwab.
That approach is particularly useful when your routine moves between checking available cash, reviewing positions, researching a security, and deciding whether an order deserves more attention. I like not having to rebuild the context in another app. The trade-off is that a wide feature set can make the first few sessions feel less immediately obvious than a focused app whose only job is tracking spending or displaying market prices.
Schwab Mobile has been available since May 25, 2011, and its long presence helps explain why it feels like a companion to a full financial relationship rather than a newly designed investing experiment. The developer is not an anonymous utility maker; the app is tied directly to Charles Schwab. That connection is important because the app makes the most sense when you already use, or are considering using, Schwab accounts.
The public response is mixed rather than spotless. It holds an average rating of 3.1 from around 29 thousand ratings, alongside roughly 13 thousand written reviews. I read that combination as a warning to keep expectations realistic: the app is established and widely used, but a large installed audience does not automatically mean every user will find the interface smooth or every workflow equally polished.
Its reach is substantial, with over 5 million installs. That tells me it is not a niche tool made only for advanced traders, but popularity should not be confused with simplicity. Someone who only wants a lightweight way to watch a few prices may find the broader Schwab environment heavier than necessary.
Cost and what “free” really means here
Schwab Mobile itself is free to download. That is the clearest value point for a person deciding whether to try it: you can install the app without paying an app-store purchase price. The free access is especially practical for existing Schwab customers who want mobile access without maintaining a separate paid companion tool.
Still, I would separate free app access from the cost of the financial products or transactions you may use through it. The app does not turn investing into a cost-free activity simply because the download has no price. Account terms, investment choices, and transaction details belong to the Schwab relationship and should be checked before acting. I would never use the word “free” as a shortcut for “risk-free” or “cost-free in every situation.”
This distinction also affects how I compare it with alternatives. A paid personal-finance app may charge for planning tools, while a brokerage app may be free to install but still require an account and involve product-specific costs. Schwab Mobile’s value comes from access to a wider financial service, not from promising that every possible activity carries no charge.
For someone who already has Schwab accounts, the calculation is straightforward: the app adds mobile convenience without a separate download fee. For someone outside that ecosystem, the question is not “Is the app free?” but “Do I want the Schwab platform behind it?” That is a more useful decision than comparing app-store prices alone.
Where the app delivers practical value
The most convincing use case is the everyday account check. Imagine receiving a payment, moving through a normal week, and wanting to review available cash before making a purchase or transferring money. A finance app that combines banking and investing context can reduce the need to remember which service holds which information. I find that useful because financial decisions often happen between categories rather than inside a single one.
Research is another area where the app can be more useful than a basic portfolio viewer. When I am considering a company or fund, I do not want to look only at a changing price. I want enough context to decide whether the idea deserves deeper research. The research and trading side of Schwab Mobile is intended for that transition from “I noticed this” to “I am evaluating this,” although I still prefer slowing down and checking the details carefully before placing an order.
A useful habit is to treat the app in two stages. I use the quick account view for orientation, then move deliberately into research before making a decision. That prevents a momentary price movement from becoming an impulsive trade. The app’s ability to put these activities close together is valuable, but it also means the user has to supply the discipline.
Another non-obvious strength is continuity. A mobile session is not just a separate calculator or news feed; it can fit into a broader Schwab workflow. If you manage several kinds of financial activity with the same provider, that continuity may be worth more than a cleaner-looking app that only handles one slice of your finances.
There is also value for people who check investments while away from a desktop. A phone cannot replace the concentration of a larger screen for every research task, but it can make routine monitoring and timely account review more convenient. I would use it for staying informed and handling ordinary account actions, not as an excuse to make constant decisions based on short-term market noise.
Research, trading, and the discipline problem
The presence of trading tools changes how I evaluate the app. A simple portfolio tracker can be passive; a brokerage app puts action close to information. That is convenient when you have already made a considered plan, but it can be a disadvantage when you are reacting emotionally. My practical advice is to decide the reason for an order before opening the trade screen, then use the app to execute or review that plan rather than inventing one under pressure.
This is where Schwab Mobile differs from many ordinary finance alternatives. Budgeting apps are usually built around spending categories, recurring bills, and cash-flow awareness. Market-only apps tend to emphasize watchlists, headlines, or price movement. Schwab Mobile is more integrated, but that integration means it asks you to understand several financial jobs at once.
I also see a trade-off between convenience and depth. A phone interface can make research accessible in a short break, yet the smaller screen can encourage skimming. If I were comparing several investments, reading extensive material, or checking a complex decision, I would rather use a larger display and take notes. The mobile app is best as part of a workflow, not necessarily the entire workflow.
One practical technique is to separate monitoring from acting. I might use the app to check whether an account needs attention, but I would avoid placing an order simply because the market moved while I was looking. That sounds obvious, but an integrated finance app makes the distance between observation and action very short. The convenience is real; so is the responsibility.
Banking and investing in one place
The banking side is important because it changes the app from an investment-only tool into a broader financial dashboard. If your cash and investments are connected through Schwab, seeing both areas in one mobile environment can make transfers, balances, and planning feel less fragmented. I find this most valuable for people who dislike maintaining separate mental ledgers for everyday money and long-term holdings.
There is a subtle benefit here: account context can improve decisions. Before moving money or buying an investment, I can think about available cash and existing positions together instead of viewing the proposed action in isolation. That does not provide financial advice, but it does make it easier to notice when a decision affects more than one part of a personal plan.
The downside is that a combined experience may feel excessive if your needs are narrow. A person who only wants a spending tracker may prefer an app designed around budgets. Someone who only wants educational market information may prefer a research service without banking functions. Schwab Mobile earns its place when the connected account experience matters.
I would also be careful about assuming that a single app removes all complexity. Financial accounts still have their own rules, and a mobile screen cannot make every decision simple. The app can organize access, but it cannot replace reading transaction details, understanding an investment, or checking the consequences of a transfer.
Who will get the most value
I think Schwab Mobile is a strong fit for existing Schwab customers who want one mobile entry point for account review, investing, research, trading, and banking. It is also suitable for a person who prefers a full-service financial relationship over assembling separate apps for cash, investments, and market research.
It can work well for a long-term investor who checks positions periodically and wants research available when a question comes up. The app is not limited to people who trade constantly; in fact, I would argue that occasional investors may benefit more if they use the research tools to slow down their decisions rather than treating the phone as a fast-action button.
It is less convincing for someone who has no interest in Schwab accounts, wants only automatic expense categorization, or expects a very minimal interface. A dedicated budgeting app may be better for household cash-flow planning. A specialized market app may be better for users who want dense charting or a particular research style. The right comparison depends on the job you need done, not on how many features can fit into one download.
Beginners should also consider their comfort with financial terminology and account decisions. The Everyone rating describes the app’s broad age suitability, but it does not mean every investing action is beginner-proof. I would recommend that a new investor explore the account and research areas first, learn what each balance represents, and postpone trading until the basic workflow feels clear.
Experienced users may appreciate the convenience, but they should judge it against their preferred research depth and execution habits. If you already rely on advanced desktop analysis, the phone may serve best as a monitoring and account-management companion. If your investing is straightforward and tied closely to Schwab, the mobile experience may cover most daily needs.
Small workflow choices that improve the experience
My first tip is to avoid opening the app with a vague intention such as “see what the market is doing.” That invites distraction. I get more value when I open it for a defined task: review cash, check a position, research a security, or inspect an account activity item. A focused purpose makes the broad interface feel more manageable.
Second, I would review the account context before acting. When banking and investing information appear in the same service, it is easy to think of available cash as interchangeable with money intended for another purpose. Taking a moment to identify which account you are viewing and why you are moving money is a simple safeguard against avoidable mistakes.
Third, use research as a pause rather than a trigger. If a price catches your attention, treat that as the beginning of a question, not the conclusion. Look at the information available in the app, compare it with your own plan, and decide whether the action still makes sense after the initial excitement fades.
Finally, use the phone for the tasks it handles comfortably. Quick reviews, routine checks, and timely account access suit a mobile screen. Extended comparisons and complicated planning deserve more time and, in my opinion, often a larger display. This division of labor lets the app remain useful without forcing it to replace every other financial tool.
My verdict: valuable access, not a universal finance solution
Schwab Mobile offers real value because the download is free and the app connects several parts of the Schwab experience in one place. Its best audience is clear: people who use or want to use Schwab for investing, research, trading, and banking, and who want that relationship available from a phone. The broad reach and established history make it a serious option, but the average rating of 3.1 also supports a measured view rather than uncritical praise.
I would choose it for integrated Schwab access, not merely because it costs nothing to install. That distinction matters. The app can make financial routines more convenient, but the underlying account choices, investment risks, and possible product-specific costs still deserve attention. Free access is a practical advantage, not a guarantee of financial value.
My main reservation is friction created by breadth. The app tries to serve banking customers, investors, researchers, and traders, so users seeking one extremely simple task may find a dedicated alternative easier. I also would not rely on a phone alone for every serious research or planning decision. The app is most effective when it supports a thoughtful process rather than encouraging constant checking.
In the end, I would recommend Schwab Mobile to a Schwab customer who wants a capable mobile companion and is willing to learn where its different areas fit together. I would tell a budgeting-first user or someone looking for a specialized trading interface to compare alternatives before committing. For the right account holder, the convenience is meaningful; for everyone else, the free download by itself is not enough reason to switch.
Gallery
Schwab Mobile Pros and Cons
- Quick access to balances
- positions
- orders
- and account activity
- Supports stock
- ETF
- mutual fund
- and options trading
- Customizable watchlists help track favorite investments
- Useful research tools
- news
- charts
- and analyst information
- Secure login options and biometric authentication are available
- Some advanced trading features are easier to find on the desktop platform
- Real-time quotes may require enrollment or market-data eligibility
- The app can feel complex for beginners managing multiple account types
- Options trading involves extra approval requirements and added risk
- Mobile performance may vary during periods of heavy market activity
Schwab Mobile Frequently Asked Questions
What is Schwab Mobile, and what can I do with it?
Schwab Mobile is Charles Schwab’s official mobile app for managing eligible brokerage, retirement, banking, and other Schwab accounts from an Android or iOS device. After signing in, users can review balances and positions, monitor market activity, research investments, place trades, transfer money, deposit checks, view statements, and contact Schwab support. Available tools can vary depending on the account type and region.
Is Schwab Mobile safe to use for banking and investing?
Schwab Mobile includes security features designed to protect account access and financial information, such as encrypted connections, login verification options, biometric sign-in on supported devices, and session controls. Even so, users should install the app only from an official app store, keep their phone and operating system updated, avoid public Wi-Fi for sensitive actions, and never share passwords or verification codes with anyone.
Can I buy and sell stocks or other investments through Schwab Mobile?
Yes, the app generally allows eligible Schwab customers to research investments and place orders for supported products, including stocks, exchange-traded funds, mutual funds, options, and other securities. Before submitting an order, review the symbol, quantity, order type, duration, estimated costs, and account selected. Trading availability, fees, permissions, and risk disclosures may differ by product and account.
Can I deposit checks and transfer money using Schwab Mobile?
Schwab Mobile typically provides convenient money-management tools, including mobile check deposit and transfers between eligible Schwab accounts or linked external accounts. Mobile deposits require clear images of the check and may be subject to endorsement rules, dollar limits, review periods, and funds-availability schedules. Transfer timing and eligibility can also depend on account verification, transaction type, and Schwab’s current policies.
Is Schwab Mobile free, and are there any requirements to use it?
Downloading Schwab Mobile is generally free, but using the app requires an eligible Charles Schwab account and valid login credentials. Standard account fees, investment expenses, service charges, or transaction-related costs may still apply according to the product and Schwab’s pricing schedule. The app also requires a compatible Android or iOS device, internet access, and enough storage for installation and updates.














